
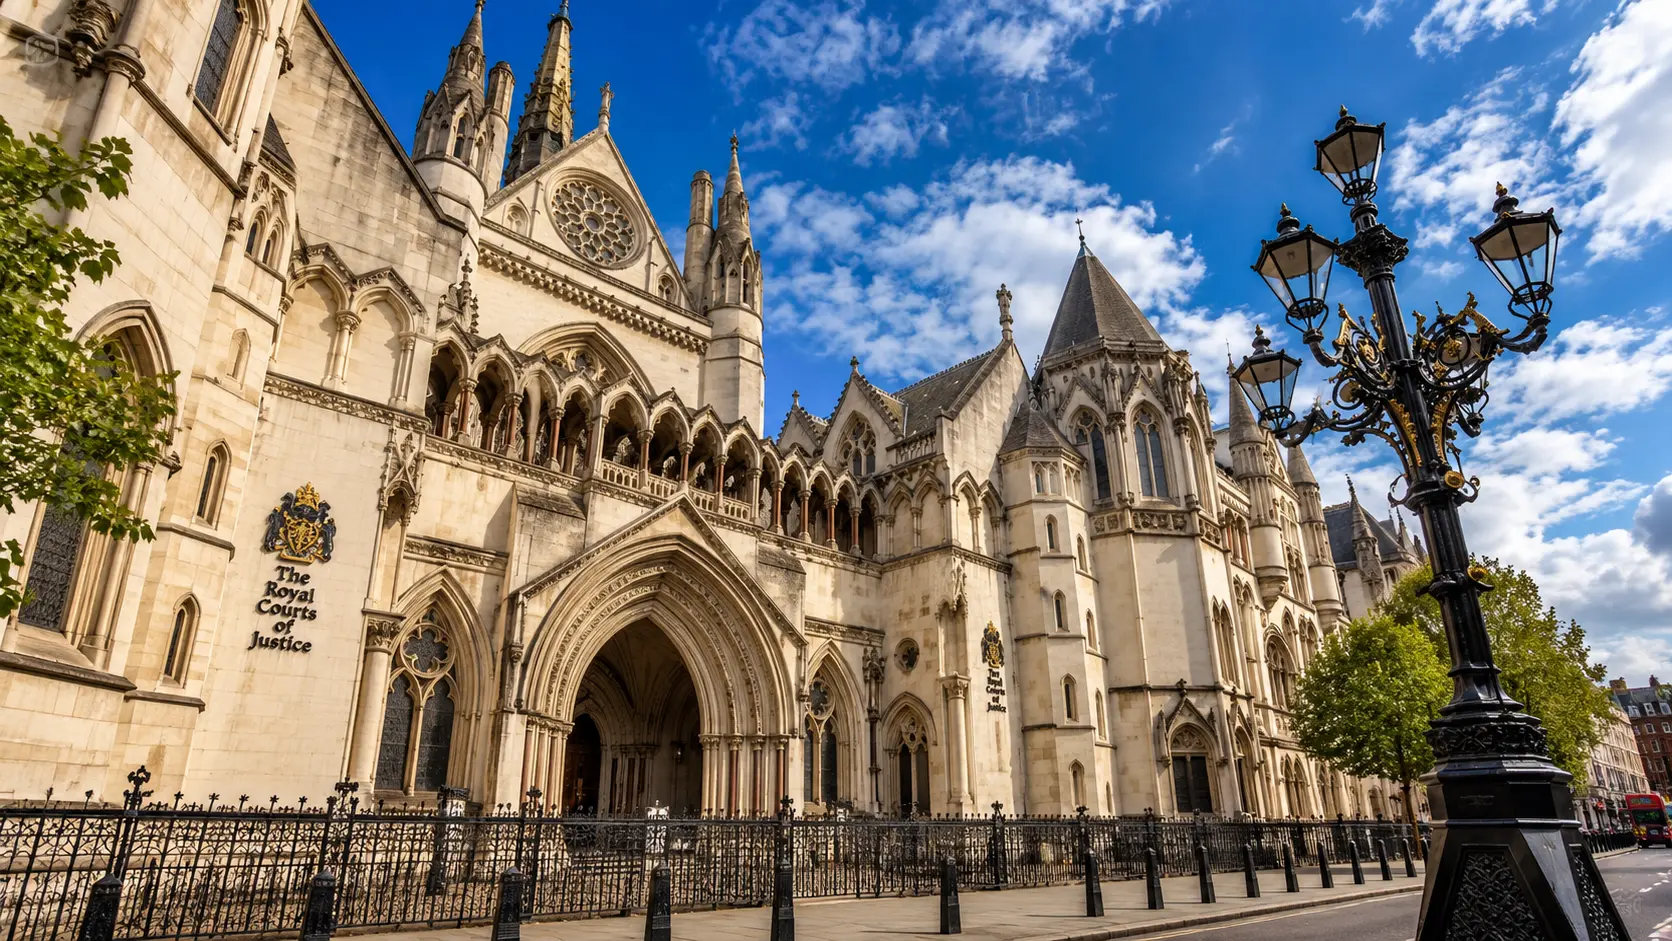

A High Court ruling on the attempted transfer of an investment partnership from England to the Cayman Islands highlights the importance of deed formalities, the limits of contractual powers of attorney and the need to follow agreed procedures when changing investors’ legal rights.
What did the High Court decide?
In 3Kings Holdings Limited v TCF 1 GP Limited [2026] EWHC 2620 (BP), handed down on 16 October 2026, HHJ Paul Matthews, sitting as a Judge of the High Court, considered a jurisdiction challenge and a claim concerning the governing law of a limited partnership.
The dispute centred on whether a Cayman Islands limited partnership agreement executed by the defendant could bind 3Kings Holdings Limited and replace the original agreement governed by English law. The defendant argued that its authority under the original agreement permitted it to carry out the change and rely on the Cayman agreement’s exclusive jurisdiction clause.
The judge concluded that the claimant remained bound by the English agreement but not by the Cayman agreement. The proper law of the original agreement had not changed, and the English court retained jurisdiction in relation to it. The court also decided that declaratory relief was appropriate, with the precise wording to be settled after the parties had considered the judgment.
The central issue was whether the general partner had valid authority to bind an existing limited partner to the replacement Cayman agreement.
How did the partnership dispute arise?
The claimant, 3Kings Holdings Limited, is a company incorporated in Malta. The defendant, TCF 1 GP Limited, is incorporated in England and Wales and acted as general partner of a private fund limited partnership operating as the Conscious Fund.
The original limited partnership agreement was executed on 26 November 2020. It provided for English law to govern the agreement and gave the English courts exclusive jurisdiction over disputes arising out of or in connection with it, subject to the clause’s stated qualifications.
3Kings later became a limited partner. The fund focused on early-stage venture capital investments in companies specialising in psychedelic medicine, with the stated aim of improving outcomes in areas including mental health, addiction and pain.
The defendant maintained that administering the partnership in England was less suitable for its investor base and operations. It cited the location of many investors and assets in the United States, the use of US currency and the perceived advantages of Cayman Islands arrangements for US investors and reporting requirements.
A new limited partnership agreement expressed to be governed by Cayman Islands law was executed on 28 August 2023 and registered with the relevant Cayman authority on 30 August 2023. It included 3Kings in Schedule A and contained a Cayman Islands jurisdiction clause.
The defendant relied on the power of attorney contained in the original agreement, asserting that it could execute documents on behalf of the limited partners. The claimant disputed whether that power had been validly created, whether it covered the proposed change and whether it had been exercised in accordance with its terms.
- The original limited partnership agreement is executed, providing for English law.
- The parties dispute the precise date and manner in which 3Kings signed the original agreement; the judgment records that it became a limited partner.
- The replacement Cayman Islands agreement is executed.
- The Cayman agreement is registered with the relevant authority.
- 3Kings issues proceedings seeking a declaration concerning the governing law of the partnership.
- The Cayman agreement is re-executed on behalf of 3Kings by the defendant, relying on the original power of attorney.
- The court hears the application and relevant part of the claim.
- The High Court hands down its judgment.
Why was the power of attorney problematic?
The defendant’s case depended on clause 26 of the original agreement, which purported to appoint the general partner and its officers as attorneys for limited partners. The clause listed documents that could be executed on their behalf, including instruments connected with parallel investment vehicles, amendments and certain reorganisations or re-filings.
The judge first considered the statutory requirements for creating a power of attorney and for executing a deed. Under the Powers of Attorney Act 1971, an instrument creating a power of attorney must be executed as a deed by the donor of the power. The relevant deed formalities were also considered under the Law of Property (Miscellaneous Provisions) Act 1989 and, in relation to companies, the Companies Act 2006.
The original agreement stated that it was executed as a deed. However, the evidence and execution arrangements raised questions about whether it had actually been validly executed as one. In particular, the judgment considered the absence of an appropriate attestation clause and the evidence concerning the witnessing of signatures.
The judge concluded that the original agreement had not been validly executed as a deed. That conclusion was important because the defendant relied on the deed-based power of attorney to execute the replacement agreement on the claimant’s behalf.
The court also considered whether the power of attorney could be effective as an ordinary written authority even if it failed as a deed. The judge examined the scope of the authority and the principles governing the construction of powers of attorney, including the requirement that an act challenged as exceeding the authority must be supported by a fair construction of the instrument.
HHJ Matthews considered that a stricter approach to interpretation was appropriate where a power was intended to be created by deed but failed because of defective execution. The intention to use that greater formality remained relevant despite the defect.
Could the partnership move to the Cayman Islands?
The court distinguished between establishing a parallel investment vehicle in another jurisdiction and changing the domicile of the existing English limited partnership.
Clause 10 of the original agreement gave the general partner powers to establish parallel investment vehicles for specified purposes. The judge accepted that the Cayman agreement could potentially fall within some of the provisions concerning documents for such a vehicle. However, that did not mean the defendant had authority to transfer the existing partnership’s governing law and domicile to the Cayman Islands.
The judge accepted the claimant’s analysis that clause 26 provided an implementation mechanism for executing documents required by local law for a reorganisation or re-filing. It did not itself confer the underlying decision-making power to re-domicile the existing partnership.
The court also considered the manner in which the Cayman agreement had been signed. Clause 26.4 contemplated signing separately as attorney for each limited partner or signing as attorney for all limited partners after listing them. The defendant instead signed for itself and for the Cayman partnership as its general partner, without identifying the limited partners as the parties on whose behalf it was exercising the power of attorney.
The judge found that the execution did not comply with the original agreement’s requirements. The defendant could not rely on the new partnership agreement’s own structure to establish the authority required to create it in the first place.
| Issue | What the judgment established |
|---|---|
| Parallel vehicle | The original agreement allowed for the establishment of parallel investment vehicles in appropriate circumstances. |
| Re-domiciliation | The power of attorney did not itself confer the power to decide to move the existing English partnership to another jurisdiction. |
| Execution | The Cayman agreement was not executed in the manner required for the defendant to act as attorney for the limited partners. |
| Material changes | Changing governing law and the forum for disputes could materially affect the partners’ rights. |
Why did execution and notice matter?
The court separately examined whether the purported use of the power of attorney would materially change the partners’ rights. The original agreement restricted certain reorganisations or re-filings where they would produce a material change in those rights.
The defendant argued that the principal differences between the English and Cayman agreements concerned governing law and jurisdiction. The judge rejected the suggestion that these differences were immaterial.
Although the two legal systems shared historical foundations, the judge found that there were significant differences between them. Moving disputes to the Cayman Islands could make litigation more difficult, costly or impractical for investors based in England or elsewhere in Europe. The choice of jurisdiction could affect the available legal representation, access to specialist judges and practical communication across time zones.
The change could also benefit some investors, depending on their location and circumstances. However, the fact that investors might be affected differently did not make the change immaterial. The place where rights could be enforced was an important consideration for someone deciding whether to invest.
The judge therefore concluded that entry into the Cayman agreement would materially change the partners’ rights for the purposes of the original agreement’s restrictions.
Notice was another issue. The original agreement required amendments to be notified promptly and prescribed methods for giving written notices. The judge considered communications sent during 2024, including emails referring to the partnership’s proposed move and a meeting at which a copy of the Cayman agreement was handed to the claimant.
Those communications did not amount to prompt notice of the completed change in August 2023 in the manner required by the original agreement. Some referred only to a process that was still underway, while others did not notify the claimant of the completed change. The judge concluded that the notification requirements had not been satisfied.
The defendant also relied on its re-execution of the Cayman agreement on 12 March 2026. The court considered the timing of the proceedings and explained that the parties’ rights at the date the claim was issued remained relevant to the jurisdiction question. The later re-execution did not displace the English court’s jurisdiction over the dispute as it stood when proceedings began.
What does the judgment mean for investment funds?
The decision illustrates the legal risks that can arise when a general partner seeks to change the structure or jurisdiction of an investment fund under powers contained in an existing limited partnership agreement.
First, the formalities for executing a deed and creating a power of attorney matter. A contractual clause intended to confer extensive authority may not deliver the intended result if the underlying instrument is not validly executed.
Second, a power to execute documents should not be confused with the power to make the substantive decision those documents are intended to implement. The scope of authority depends on the actual wording of the agreement and the purpose for which the authority was granted.
Third, a move to a different governing law and court system may materially affect investors’ rights even if much of the wording in the replacement agreement remains similar. The choice of governing law and forum can influence the cost, convenience and practical enforceability of contractual rights.
Finally, agreed execution and notification procedures must be followed. A general partner should not assume that an announcement of a proposed restructuring, or a later delivery of the relevant agreement, automatically satisfies contractual requirements for formal written notice of a completed change.
The judgment does not establish that investment partnerships can never move jurisdictions. Rather, it demonstrates that the authority, contractual restrictions, execution formalities and notice requirements must be assessed against the terms of the particular partnership agreement.
Frequently asked questions
What was the main issue in 3Kings Holdings Limited v TCF 1 GP Limited?
The main issue was whether the defendant could use a power of attorney in the original English-law limited partnership agreement to bind 3Kings Holdings Limited to a replacement agreement governed by Cayman Islands law.
Did the High Court accept that the Cayman agreement replaced the English agreement?
No. The court concluded that the claimant remained bound by the English agreement but was not bound by the Cayman agreement. The governing law of the original agreement had not changed.
Why was the power of attorney important?
The defendant relied on it to execute documents on behalf of the limited partners. The court found that the original agreement had not been validly executed as a deed and that the purported exercise of the power did not comply with its requirements.
Could the general partner establish an investment vehicle in another jurisdiction?
The original agreement contained powers to establish parallel investment vehicles. However, the judge distinguished those powers from authority to re-domicile the existing English partnership. The scope of any authority depends on the agreement’s terms.
Why did the court consider the change of jurisdiction material?
The choice of governing law and forum could affect where and how investors enforce their rights, including litigation costs, access to legal representation and the practicalities of proceedings in another jurisdiction.
When was the judgment handed down?
The judgment in 3Kings Holdings Limited v TCF 1 GP Limited [2026] EWHC 2620 (BP) was handed down on 16 October 2026 by HHJ Paul Matthews, sitting as a Judge of the High Court.